Do I Need Umbrella Insurance: Who Benefits, What It Costs, and When It Is a Waste of Money
Riskado
Whether you need umbrella insurance depends on five facts: the liability risks in your household, the limits on your auto, home, renters or boat policies, the assets and income a judgment could reach, the insurer's eligibility rules, and your state's law. Umbrella insurance is an optional layer of liability coverage above those underlying policies. It can respond when a covered judgment or settlement is larger than an underlying limit, and it can cover some personal-injury claims, such as libel or slander, that ordinary policies leave out, according to the NAIC (opens in a new tab) and the Insurance Information Institute (opens in a new tab). Your actual policy form decides what is covered.
Key takeaways
- What it isAn optional layer of liability coverage above your auto, home, renters or boat policies.
- When it respondsWhen a covered judgment or settlement is larger than an underlying limit, up to the umbrella's own limit.
- What else it can coverSome personal-injury claims, such as libel or slander, that ordinary policies leave out.
- What decides whether you need oneYour household's liability risks, your current limits, the assets and income a judgment could reach, the insurer's eligibility rules and your state's law.
- What settles coverageYour actual policy form.
What does umbrella insurance do?
An umbrella is excess liability insurance. State insurance departments publish their own definitions; the Connecticut Insurance Department glossary (opens in a new tab), for example, defines umbrella liability insurance as coverage for losses above the amounts paid by your other liability policies, and it can sometimes protect an insured who is not covered by the usual liability policies.
Your auto, homeowners, renters, boat or landlord policy pays first, up to its own limit. If a covered claim is larger than that limit, the umbrella can respond up to its own limit. Depending on the policy, an umbrella covers bodily injury to others, property damage to others, personal-injury claims such as libel, slander, defamation and invasion of privacy, and legal defense costs (Travelers (opens in a new tab)). It is liability coverage only, so it does not pay to repair your own house, car or boat.
Excess liability and umbrella can overlap, but the terms and scope vary by insurer, so the form itself tells you what you are buying.
What decides whether you need one?
Start with a short inventory. The Insurance Information Institute and Progressive both point to the same kinds of facts, and you can answer most of them from your own paperwork:
- What could a judgment reach? Assets, income and future earnings are all part of that.
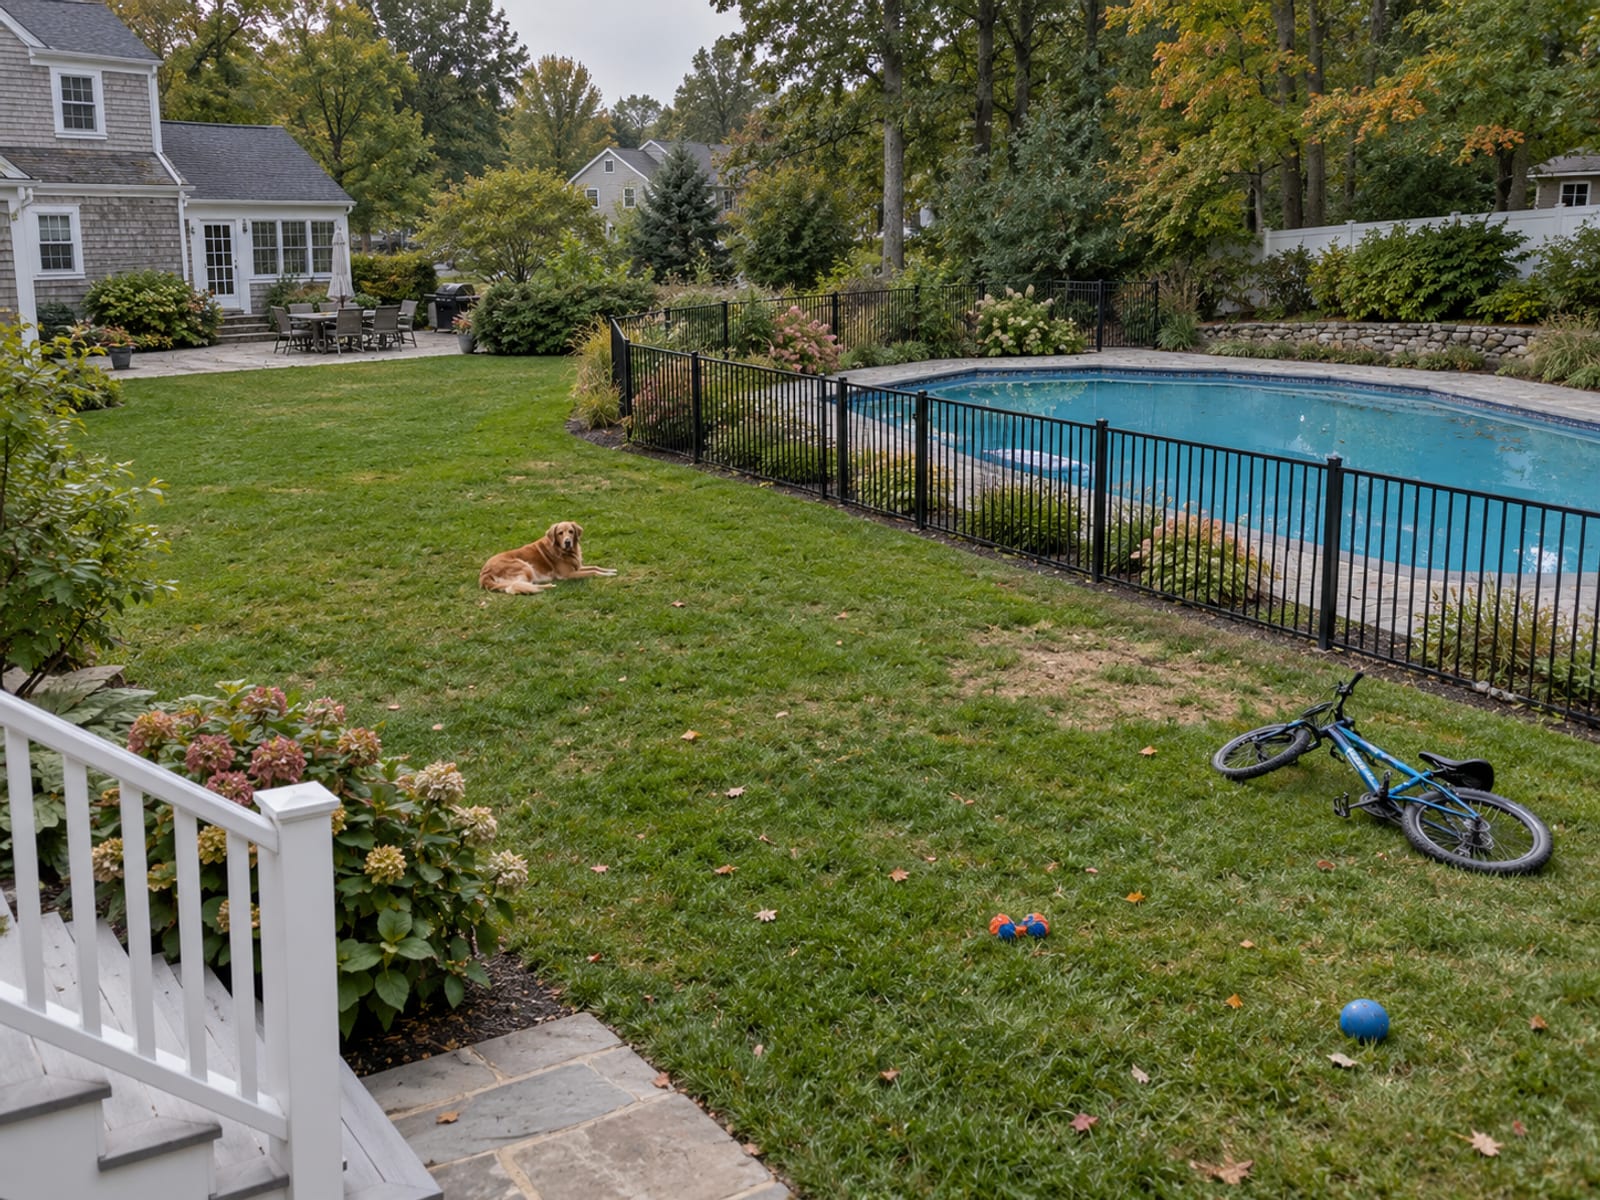
- What could cause a large claim? A swimming pool, pool parties, a dog, a teenage driver, a boat or other recreational vehicle, multiple homes or vehicles, and a rental property are the exposures the Travelers (opens in a new tab) and Insurance Information Institute (opens in a new tab) pages name. A state regulator may raise the same point; for example, the Connecticut Insurance Department's pool-owner notice (opens in a new tab) refers pool owners to a discussion of personal umbrella coverage.
- What are your current liability limits? Pull the declarations pages for each policy.
- Do you have public-facing activities or a business? A personal umbrella excludes business activity; more on that below.
None of these facts proves you need an umbrella. They tell you what to bring to a licensed agent so the two of you can look at your exposure against your limits. A household with a pool, a teen driver and a rental unit has a different conversation than a renter with one car, and the answer to "is it worth it" is the premium set against your own exposure, which is what the agent can quote.
What does an umbrella policy exclude?
The common exclusions are damage to your own home, vehicle, boat or personal property, business losses and business activity, intentional acts, criminal conduct and contractual liability, per Travelers (opens in a new tab) and Allstate (opens in a new tab). Any loss excluded by the umbrella or the underlying policy stays excluded, and a claim made when required underlying insurance is absent or not maintained can also fall outside coverage.
Business losses and business activity are excluded from Travelers' personal umbrella. A business owner looks at a commercial umbrella instead, which GEICO (opens in a new tab) describes as written over business liability policies such as general liability and commercial auto. If you run a business from home, ask whether home-based business activity is excluded.
Some limits are specific to the insurer, such as restrictions on vehicles, drivers, animals, properties, boats and rentals. A missing detail is a question for the agent: which animals, vehicles or rentals does this form restrict?
What underlying limits and eligibility rules apply?
Underlying limits are each insurer's rule, not a legal requirement for personal umbrellas. Most insurers want at least $250,000 of auto liability and $300,000 of homeowners liability before they sell a $1 million umbrella, according to the Insurance Information Institute (opens in a new tab). The exact requirements depend on the insurer, per Allstate (opens in a new tab).
GEICO's published requirements (opens in a new tab), dated August 31, 2026, show how specific they get:
- Auto, option one: $300,000 per person and $300,000 per occurrence for bodily injury, with $100,000 for property damage.
- Auto, option two: $250,000 per person and $500,000 per occurrence for bodily injury, with $100,000 for property damage.
- Homeowners: $300,000 liability.
- Boats: $100,000 liability for boats under 26 feet and under 50 horsepower, and $300,000 for boats 26 feet or longer or 50 horsepower and above.
Hover or tap a row to highlight it.
| Underlying policy | Requirement | Source |
|---|---|---|
| Auto, option one | $300,000 per person and $300,000 per occurrence for bodily injury, with $100,000 for property damage | GEICO (opens in a new tab) |
| Auto, option two | $250,000 per person and $500,000 per occurrence for bodily injury, with $100,000 for property damage | GEICO (opens in a new tab) |
| Homeowners | $300,000 liability | GEICO (opens in a new tab) |
| Boats under 26 feet and under 50 horsepower | $100,000 liability | GEICO (opens in a new tab) |
| Boats 26 feet or longer or 50 horsepower and above | $300,000 liability | GEICO (opens in a new tab) |
Eligibility can also depend on whether every household vehicle and driver is disclosed, whether the required underlying policies are active, and whether the insurer accepts your properties, boats, animals, rental units and drivers. Claims, violations, loss history and location go into the insurer's underwriting review. If your current limits fall below the insurer's requirement, raising them adds its own premium, per Progressive (opens in a new tab).
How much does umbrella insurance cost?
Published figures give a range, and your premium will differ. AFI (opens in a new tab) puts the average at $150 to $300 a year for a $1 million personal umbrella, about $75 for the next million and about $50 for each million after that. Progressive (opens in a new tab), on a page updated September 12, 2024, cites an ACE Private Risk Services report with an average of $383 a year for $1 million for an individual with one home, two cars and two drivers, and about $75 for each additional million.
Hover or tap a row to highlight it.
| Source | Average for a $1 million personal umbrella | Each additional million | Date |
|---|---|---|---|
| AFI (opens in a new tab) | $150 to $300 a year | About $75 for the next million, about $50 for each million after that | Accessed September 2026 |
| Progressive (opens in a new tab), citing an ACE Private Risk Services report | $383 a year for an individual with one home, two cars and two drivers | About $75 | Page updated September 12, 2024 |
Personal umbrellas are commonly sold in $1 million increments up to $5 million (Allstate (opens in a new tab)). Cost depends on location, the limit you choose, the number and type of vehicles, homes, boats and other vehicles, claims, violations, credit history where permitted, your underlying limits and the insurer's underwriting.
How does an umbrella compare with raising auto and home limits?
Raising your auto or homeowners liability limit increases what those policies pay. An umbrella adds a separate layer above the underlying policies and can include personal-injury coverage, such as libel or slander, that the primary policies do not, depending on the form (Insurance Information Institute (opens in a new tab)).
Neither is better in every case, and these questions sort it out for your household:
- What is the highest liability limit each primary policy offers, and what does it cost?
- What underlying limits does the umbrella require?
- Does the umbrella follow the underlying coverage, or is it broader?
- Do defense costs sit inside or outside the limit?
- Does it cover personal-injury claims the primary policies exclude?
- Is there a self-insured retention if a gap appears?
- What is the added cost of keeping every required underlying policy in place?
Does an umbrella protect retirement accounts or trust assets?
An umbrella is liability insurance, and it does not create a creditor exemption. Whether a 401(k), IRA or trust asset can be reached by a judgment creditor is decided by state and federal law, the type of account, who owns it, the exceptions, and the facts of the judgment.
Each state writes its own exemption statutes, so the list of protected accounts and its exceptions depend on where you live. For example, Connecticut's § 52-321a (opens in a new tab) protects specified retirement plans, IRAs and certain annuity contracts from creditor claims, subject to exceptions, and § 52-352b(13) (opens in a new tab) exempts assets in, or payments from, those plans; our Connecticut umbrella insurance guide covers that state in more detail. Neither statute makes every trust or retirement-related asset safe in every judgment, and an attorney in your state can tell you how your accounts are treated.
If you live elsewhere, New York CPLR § 5205 (opens in a new tab) protects certain trust, custodial, annuity, insurance, retirement and IRA interests, with provisions on income and payments and with exceptions. Massachusetts General Laws chapter 235, § 34A (opens in a new tab) exempts specified ERISA plans, Keogh plans, qualified corporate plans, SEP plans, 403(b) plans, IRAs and annuities from execution, subject to divorce, support, criminal-penalty and restitution exceptions. An attorney can analyze ownership, trust terms and the type of judgment for your situation.
What happens when you make a claim?
You report the claim to the underlying insurer and follow the policy's notice requirements. The underlying policy investigates, defends, settles or pays a covered claim up to its limit. If the covered claim is larger than the required underlying limit, the umbrella can respond up to its own limit. An umbrella can pay liability and legal defense costs above what the primary policy pays, according to the NAIC (opens in a new tab).
How a covered claim moves through your policies
- Report the claimTell the underlying insurer and follow the policy's notice requirements.
- The underlying policy respondsIt investigates, defends, settles or pays a covered claim up to its limit.
- The umbrella responds above the limitIf the covered claim is larger than the required underlying limit, the umbrella can respond up to its own limit.
- The form's conditions applyExclusions, exhaustion requirements, cooperation duties and settlement and defense provisions all apply.
If the underlying policy excludes the claim, and the umbrella does not offer broader or drop-down coverage, you can face a gap or a self-insured retention. The umbrella's conditions, exclusions, exhaustion requirements, cooperation duties, settlement provisions and defense provisions all apply. Whether defense costs reduce the liability limit varies by policy form, so ask for the actual form and read that section.
What happens if an underlying policy lapses, is cancelled or is not renewed?
An umbrella can require the underlying policy to stay active, and it may not respond as you expect if required insurance is missing. Find the maintenance-of-underlying-insurance condition in your form before you change auto or home insurers.
Notice rules for cancellation and nonrenewal are set by each state's law and enforced by its insurance department (opens in a new tab), and which rule applies depends on the type of policy and risk. For example, the Connecticut Insurance Department's Bulletin PC-42-09 (opens in a new tab) identifies the governing statutes there, including Conn. Gen. Stat. §§ 38a-170 (opens in a new tab) and 38a-323 through 38a-326 (opens in a new tab), and a notice that does not comply is invalid. After you receive a notice, read it alongside your policy conditions and your state insurance department's rules.
What should you ask an agent?
Bring your declarations pages, a list of household drivers and vehicles, a list of homes, rental properties, boats, animals, pools and recreational vehicles, your claims and violation history, and any existing umbrella or excess policy. Then ask:
- Which underlying policies must I maintain, and at what limits, for auto, homeowners, renters, boat, motorcycle, RV and landlord coverage?
- Must every household driver and vehicle be listed?
- Are short-term rentals covered?
- Are business activities, including home-based business, excluded?
- Are libel, slander, defamation and invasion-of-privacy claims covered?
- Are intentional acts, criminal acts, contractual liability or punitive damages excluded?
- Are defense costs inside or outside the limit?
- Is there a self-insured retention?
- What happens if an underlying policy lapses, is cancelled, is not renewed, or moves to a new insurer?
- Are young drivers, permissive drivers, domestic partners and children away at school covered?
- Are particular dogs, vehicles, boats or properties restricted?
- Is coverage worldwide?
- Is this a personal umbrella, a commercial umbrella or excess liability, and which form and endorsements apply?
Check what you know about umbrella insurance
Frequently asked questions
What are the disadvantages of an umbrella policy?
The costs to plan for are the umbrella premium and any added premium for raising underlying limits to meet the insurer's requirement. The other trade-offs are the exclusions above and the condition that required underlying policies stay in force.
How much should a $1 million umbrella policy cost?
Published averages range from $150 to $300 a year (AFI) to $383 a year for one household profile (Progressive, updated September 12, 2024). Your location, vehicles, homes, claims history and underlying limits move the number, and an agent can quote it from your details.
Do I need an umbrella if I have a trust?
An umbrella responds to covered liability, and a trust is a separate legal tool. Whether a trust asset is reachable depends on the trust terms and the law that applies, which is an attorney's question.
Does umbrella insurance protect a 401(k)?
Creditor protection for a 401(k) comes from state and federal exemption law, for example Connecticut's § 52-321a (opens in a new tab), and the umbrella is insurance on top of that. Ask an attorney how your account is treated.
Your next step
Take the questions above and your declarations pages to a licensed agency in your state; you can start with Riskado's insurance agency directory. Check the agent on your own state insurance department's license lookup (opens in a new tab) before you share details.
Terms used in this guide
Tap a term to see what it means.
Umbrella insurance. An optional layer of liability coverage above your other liability policies.
Excess liability. Coverage for losses above the amounts paid by your other liability policies. Terms and scope vary by insurer.
Underlying policy. The auto, homeowners, renters, boat or landlord policy that pays first, up to its own limit.
Underlying limit. The liability amount an insurer requires you to carry on an underlying policy before it sells an umbrella.
Self-insured retention. An amount you pay yourself if a gap appears and the umbrella does not drop down to cover it.
Declarations page. The page of a policy that lists your coverages and limits.
Personal-injury claim. A claim such as libel, slander, defamation or invasion of privacy, which ordinary policies can leave out.