Alabama FORTIFIED Roof: The Insurance Discount Alabama Law Requires, Strengthen Alabama Homes Grants, Roof, Silver and Gold Levels and How to Apply
Riskado
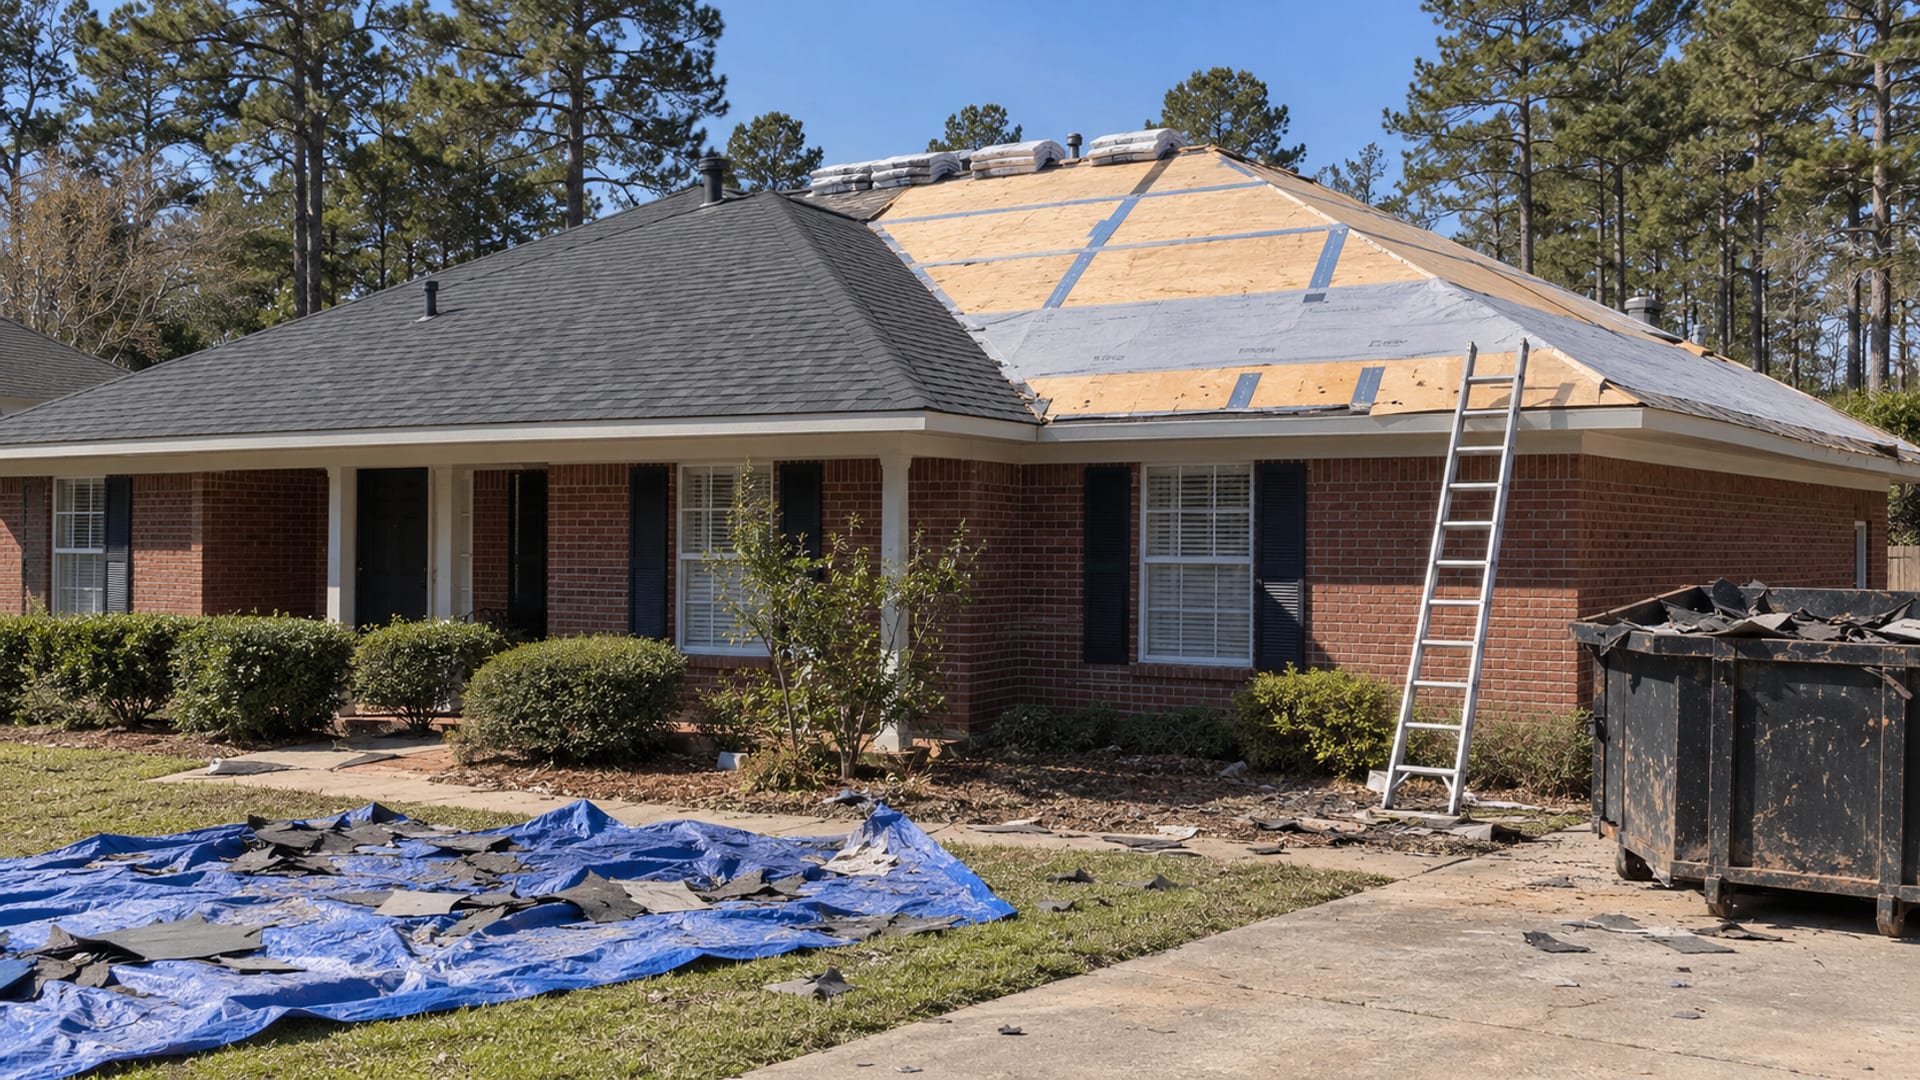
Alabama law requires insurance companies to give a premium discount or rate reduction on homes certified to an IBHS FORTIFIED standard, under Code of Alabama § 27-31D-1 (opens in a new tab) for new homes and § 27-31D-2 (opens in a new tab) for existing homes. The discount applies to the wind portion of your Alabama homeowners insurance premium, not the whole policy. FORTIFIED Roof is the first level, Silver adds protection for windows, doors and other openings, and Gold adds a continuous load path through the house. The Strengthen Alabama Homes (opens in a new tab) program states that its grants pay 100% of the cost of reaching FORTIFIED Roof, up to $10,000, as of October 13, 2026, for eligible homeowners in counties on its current schedule while funds last. To get the discount, you hand the IBHS certificate to your insurer.
Key takeaways
- The lawInsurers must give a premium discount or rate reduction on homes certified to an IBHS FORTIFIED standard.
- What it applies toThe wind portion of the premium, not the whole policy.
- The levelsRoof, then Silver for openings, then Gold for a continuous load path.
- The grantStrengthen Alabama Homes pays 100% of reaching FORTIFIED Roof, up to $10,000, as of October 13, 2026, while funds last.
- The proofGive your insurer the IBHS certificate.
What to know before you pay for a FORTIFIED roof
Two separate things are going on, and it helps to keep them apart. The insurance discount is a legal requirement on insurers once your home holds a FORTIFIED designation. The grant is a state program with its own eligibility rules, application windows and limited funding. You can get the discount without the grant, but you can't get the discount without the certificate.
The certificate is what makes the work count. A roofer's statement that a roof is "built to FORTIFIED" isn't enough. A certified FORTIFIED evaluator documents the work, IBHS reviews it and issues a designation certificate, and the insurer applies the discount after you give it that certificate. Under § 27-31D-1 (opens in a new tab), evidence of IBHS certification must be presented to the insurer before the discount takes effect.
If you're replacing a roof anyway, plan for the evaluation before the old roof comes off. The evaluator needs to document the work as it happens.
How much is the Alabama FORTIFIED insurance discount?
ALDOI publishes benchmark discounts by level and roof age. These come from ALDOI Bulletin 2016-07 (opens in a new tab) and are restated in the ALDOI and University of Alabama report on FORTIFIED homes in Hurricane Sally (opens in a new tab), published May 5, 2025, which says admitted insurers are required to apply them to the wind portion of homeowners premiums.
Hover or tap a row to highlight it.
| FORTIFIED level | Existing home, roof more than 5 years old | New or existing home, roof 5 years old or less |
|---|---|---|
| FORTIFIED Roof | 20% | 35% |
| FORTIFIED Silver | 35% | 45% |
| FORTIFIED Gold | 40% | 50% |
IBHS describes the same discounts in ranges on its Alabama incentives page (opens in a new tab), as of October 13, 2026: 25% to 35% for Roof, 35% to 45% for Silver and 45% to 55% for Gold, off the wind portion of the premium. When ALDOI announced Bulletin 2016-07 on December 23, 2016, it described discounts of 35% to 60% on the hurricane portion of the premium and 20% to 35% on the other wind portion, depending on the structure and county.
The percentage is taken from the wind portion, so the dollar saving depends on how much of your premium is wind. ALDOI estimated in that 2016 announcement that hurricane and wind exposure makes up about 70% to 80% of homeowners insurance cost on the coast and about 40% to 60% upstate. The statute also allows an insurer that doesn't separate its wind premium in its rate filing to apply the discount to the total premium, under § 27-31D-1(j) (opens in a new tab).
The insurer matters. Strengthen Alabama Homes tells homeowners to make sure the company is an admitted carrier, because admitted carriers must honor the certificate and surplus lines carriers are not obligated under the law to give the discount.
Which FORTIFIED level fits your project: Roof, Silver or Gold?
The levels build on each other. Each one includes everything in the level below it.
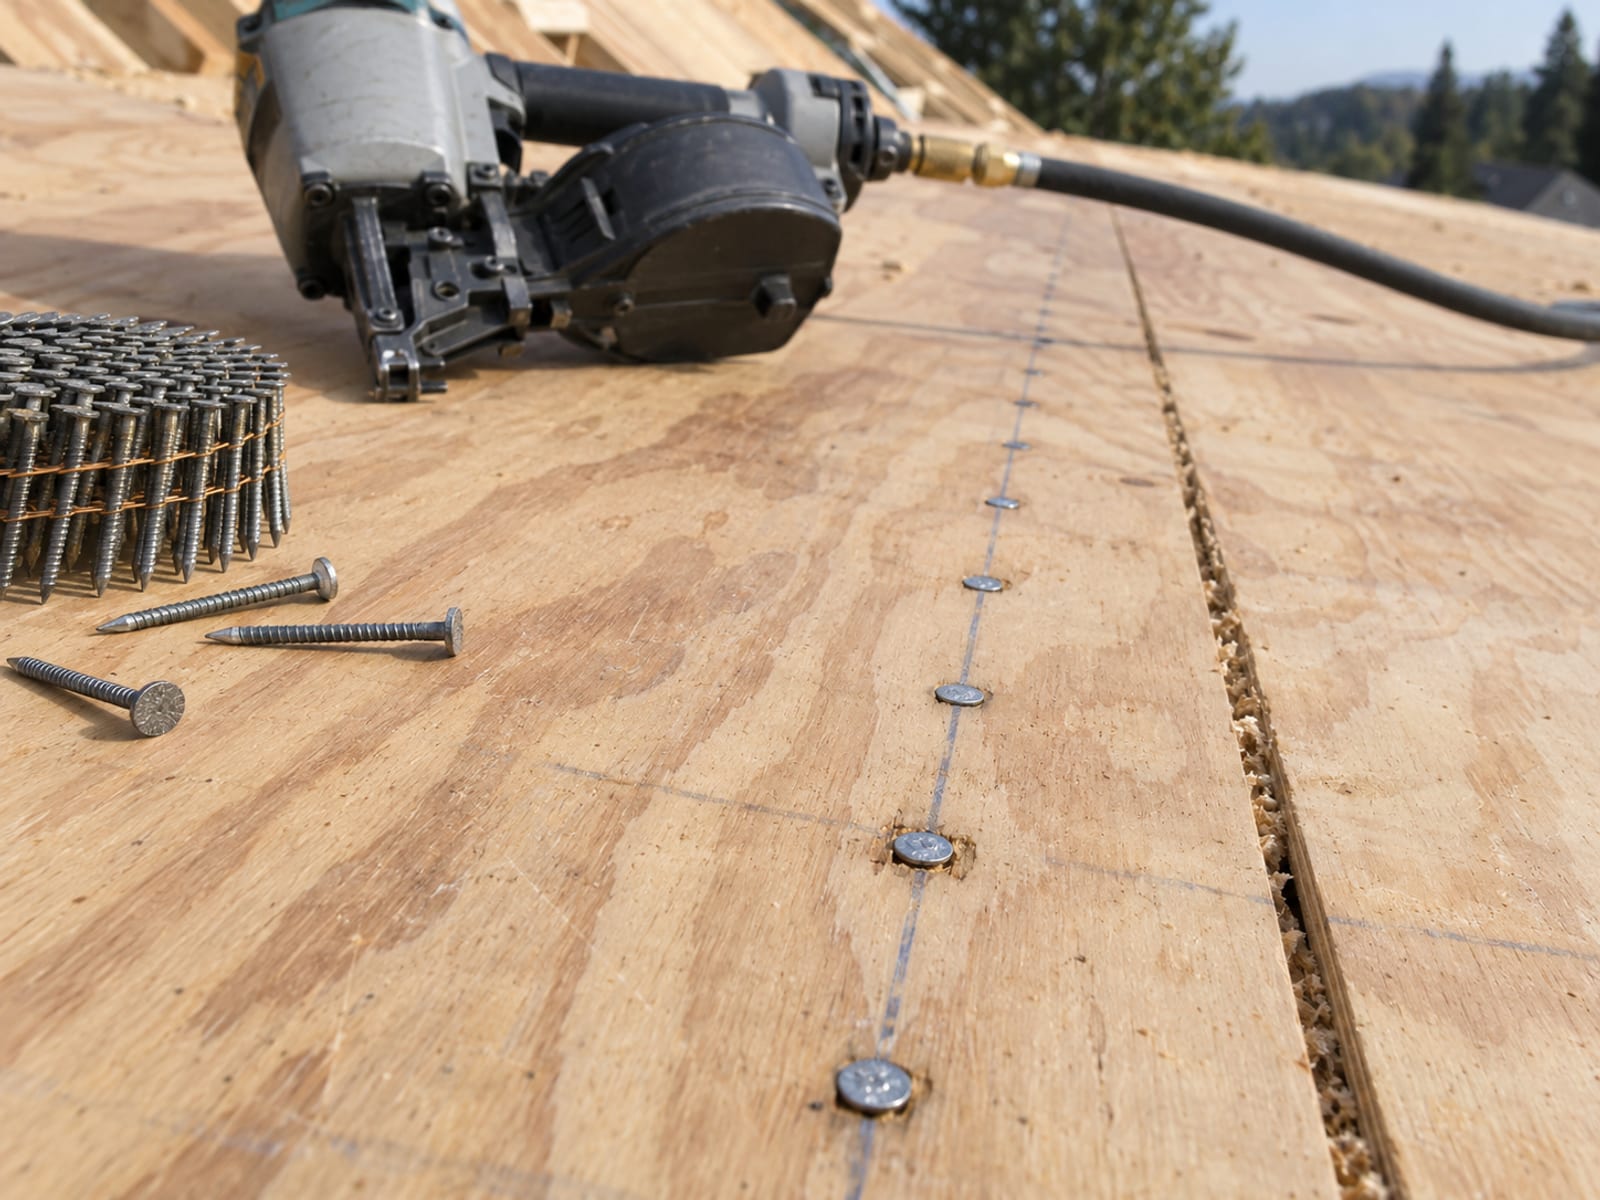
FORTIFIED Roof strengthens the roof system and limits the chance of water getting into the house if the roof covering is damaged. It addresses three main weak points, the roof deck-to-house connections, the roof edges and gaps in the roof deck, according to IBHS's FORTIFIED Roof page (opens in a new tab).
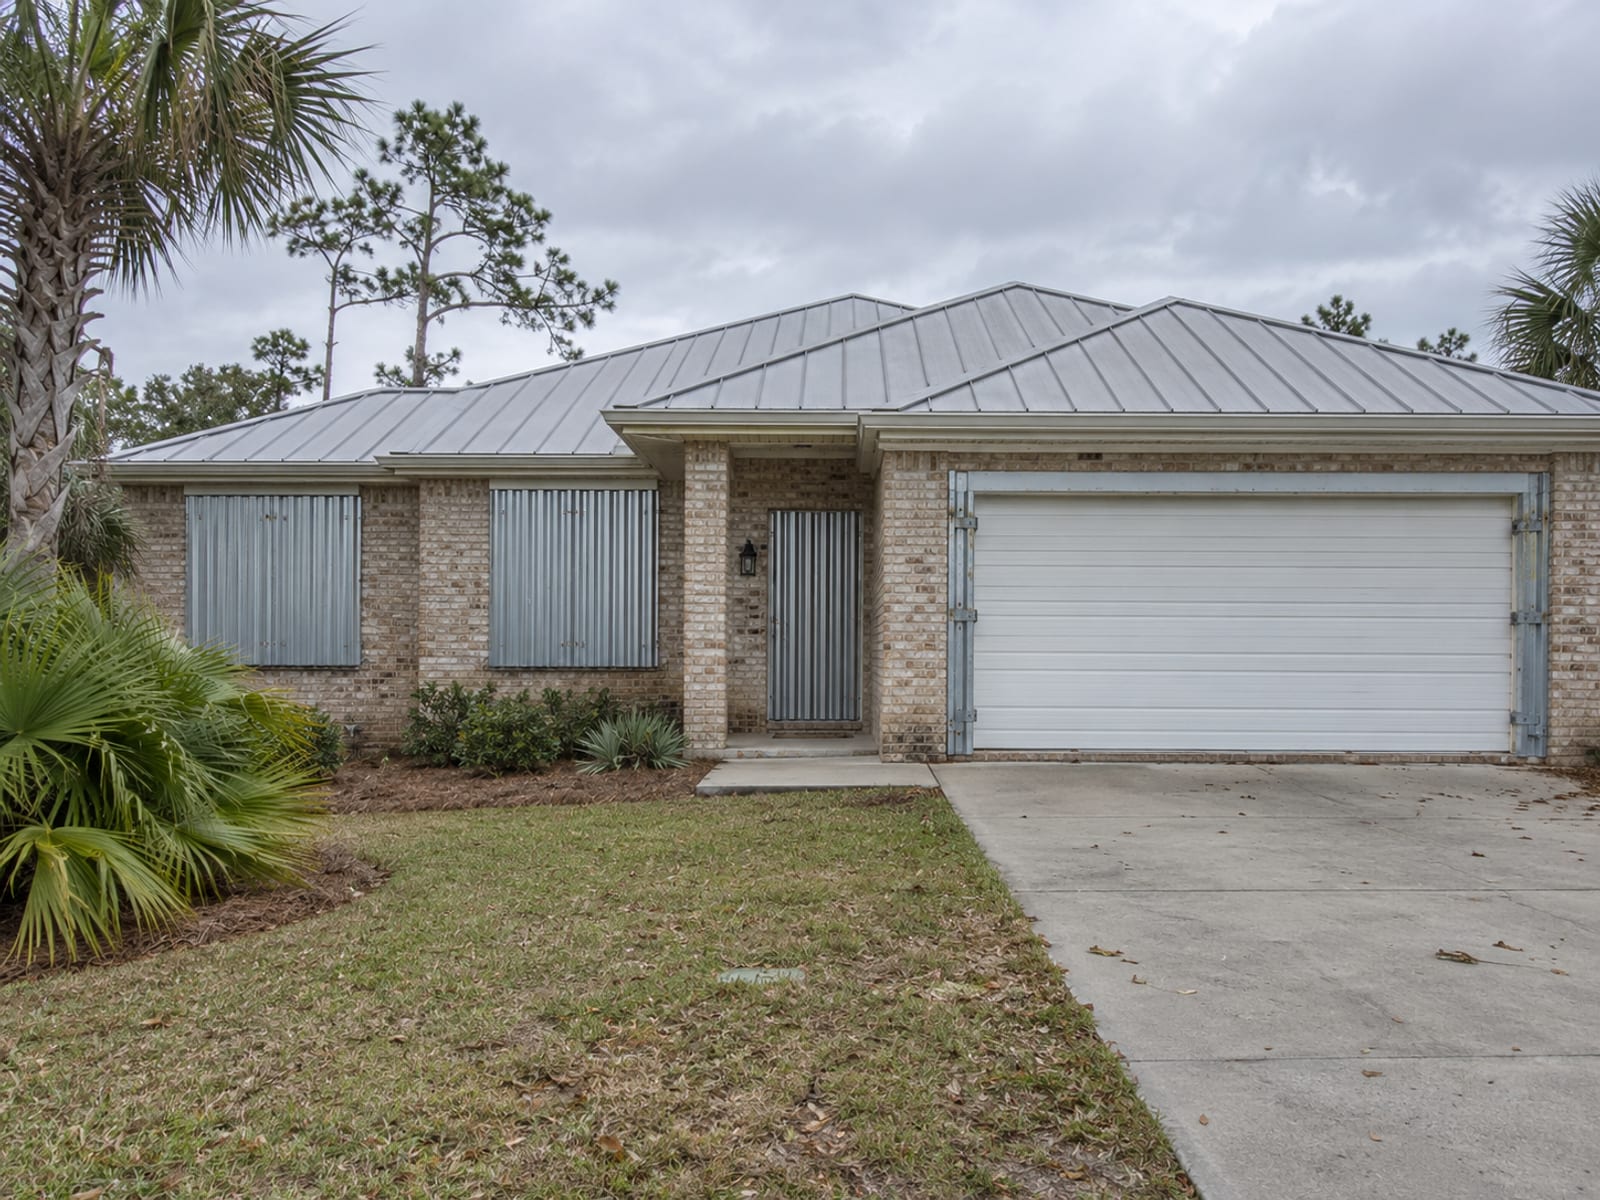
FORTIFIED Silver adds protection for windows, doors, garage doors and other vulnerable areas, so wind and rain are less likely to cause serious damage. FORTIFIED Gold adds a continuous load path that ties the roof, walls and foundation together, which IBHS describes as maximum protection from wind on its Alabama incentives page (opens in a new tab).
The standard itself changed recently. All projects permitted on or after November 1, 2025 must meet the 2025 FORTIFIED Home Standard, and where roof permits aren't required, roofs installed on or after that date must meet it, according to IBHS's technical documents page (opens in a new tab). Ask your evaluator which version applies to your project.
Who can get a Strengthen Alabama Homes grant?
The grant covers FORTIFIED Roof only. The Strengthen Alabama Homes FAQ (opens in a new tab), updated March 26, 2026, says the program doesn't offer the Silver standard and won't fund a home already at the Roof level to reach Silver. The program is run by the Alabama Department of Insurance and funded by the insurance industry in Alabama, not the state's general budget or a federal program.
The program page (opens in a new tab) sets these conditions, as of October 13, 2026:
- You live in a county on the current grant schedule and claim the home as your primary residence.
- The home is an existing, owner-occupied, single-family house. Rentals, townhomes, condominiums and mobile homes don't qualify.
- The home is in good repair and isn't listed for sale during the process.
- You have an in-force homeowners policy before the grant is paid and wind coverage in force when the work is finished.
- You carry flood insurance if the home is in a special flood hazard area.
- You upload income verification, your insurance declarations pages and a notarized vendor disclosure form.
Two more rules from the FAQ catch people. A roof insurance claim within the past six months makes you ineligible, because the program can't combine grant money and claim money for the same work. And only one grant is allowed per address.
When applications open
Funding is released by county and by quarter, and the application system closes when the money for that period is spoken for. The grant award schedule (opens in a new tab), as of October 13, 2026, lists openings at 9:00 a.m. on October 6, 2026 for Mobile County and October 8, 2026 for Baldwin County, followed by Mobile and Baldwin openings in January, April and July 2027. Applications are taken first come, first served. The program's home page also announced grants for Jefferson, Tuscaloosa and Escambia counties opening November 4, 2025, the first time the program offered grants outside Mobile and Baldwin since it began in 2015.
Policyholders of the Alabama Beach Pool have a separate route. Through the AIUA and Strengthen Alabama Homes partnership (opens in a new tab), a homeowner with an in-force AIUA policy on a single-family, detached primary residence in Baldwin or Mobile County can apply for a grant of up to $10,000 regardless of income, with proof of income required, and the home must meet the FORTIFIED Roof or Silver standard when the work is done.
Strengthen Alabama Homes is open to eligible owners by county, not by age. If you're an older or lower-income homeowner, call the program at 1-800-433-3966 and ask whether another assistance program applies to your county.
How to apply for the grant, step by step
The Strengthen Alabama Homes (opens in a new tab) process has several seven-day deadlines, and the program says it won't call you, so watch your email.
- Create an online profile and submit the application.
- Within seven days, upload your last year's federal Form 1040 or 1040-SR (or your Social Security benefit statement), your homeowners, wind and, if required, flood declarations pages, and the notarized vendor disclosure form.
- Wait for staff to review the documents.
- Within seven days of approval, choose a FORTIFIED evaluator approved by the program.
- Pay for and complete the evaluation. You receive a pass or fail, and homes that fail aren't eligible.
- Within seven days, choose three program contractors to bid on the work.
- After all three bids arrive, you receive your grant award and any out-of-pocket amount.
- Within seven days, select your final bid and sign the contract directly with the contractor.
- The contractor completes the work, and the evaluator documents it and submits it to IBHS.
- IBHS issues the FORTIFIED designation certificate.
- The program pays the grant directly to the contractor, up to the award amount.
- Take the certificate to your insurance agent, then upload the new declarations page showing the discount to your grant portal.
According to the FAQ, bids are good for 90 days, and the work must be finished within 90 days of the grant award. The contract is between you and the contractor, and any cost above the award, including rotten decking found when the old roof comes off or an upgraded shingle, is yours to pay. The program doesn't reimburse work already completed.
Deadlines and time limits to watch
- 7 daysTo upload documents, choose an evaluator, choose three contractors and select your final bid.
- 90 daysHow long contractor bids stay good.
- 90 daysTo finish the work after the grant award.
- 6 monthsA roof claim in this period makes you ineligible for the grant.
- 5 yearsHow long a FORTIFIED certificate is valid.
- 1 yearGrace period to redesignate before an extra $50 fee.
What does a FORTIFIED evaluation cost?
The evaluation fee is set by each evaluator and paid by the homeowner. The program page tells applicants that fees vary and to get several prices before choosing, and the FAQ says the fee isn't refunded if you leave the program. A list of approved evaluators with contact information is on the Strengthen Alabama Homes evaluators page (opens in a new tab). Ask each one what the fee covers, including any return visits during the work.
What happens after certification
Give your insurer or agent the IBHS certificate. The FAQ says the certificate issued by IBHS and supplied by your evaluator is all the insurance company should need to apply the wind mitigation discount. Then check your next declarations page for the discount and compare it with the previous one.
If the discount doesn't appear, ask the insurer which wind mitigation rating rule it applied and when the change takes effect. ALDOI's guidance after Hurricane Nate (opens in a new tab) tells homeowners to file for the discount after receiving the IBHS certificate and to contact the department if they have trouble getting it. ALDOI Consumer Services can be reached at 334-241-4141 or 1-800-433-3966, or ConsumerServices@insurance.alabama.gov, according to its contact information (opens in a new tab).
How roof age, claims and deductibles fit in
Roof age changes the benchmark. The ALDOI table gives a higher discount when the roof is five years old or less, and an existing home with a roof more than five years old earns the lower figure for its level.
A FORTIFIED designation doesn't change your deductible on its own. Your wind, hail or hurricane deductible is still set by your policy, and so is the way the roof is valued after a claim, whether replacement cost or actual cash value. Ask your agent about both.
A FORTIFIED endorsement is a different product. Under Code of Alabama § 27-31D-2.1 (opens in a new tab), insurance companies writing homeowners insurance must offer an endorsement that upgrades an eligible non-FORTIFIED home to the FORTIFIED standard when covered damage requires the roof to be replaced, a situation our article on whether homeowners insurance covers roof replacement walks through. IBHS notes that the cost of the endorsement varies by carrier. If you can't get a FORTIFIED roof before the next storm season, ask whether your policy includes it.
How long the designation lasts and whether it transfers
A FORTIFIED certificate is valid for five years, and a redesignation is needed to keep it, according to IBHS's redesignation page (opens in a new tab). The redesignation mainly checks the remaining life and condition of the roof covering, and if nothing substantial has changed, it may only need an inspection.
Don't let it lapse for long. A redesignation submitted after the one-year grace period costs an extra $50 processing fee, and once five years have passed since the designation expired, the home needs a complete new evaluation, according to IBHS's renewal page (opens in a new tab).
The designation belongs to the house. IBHS issues the certificate to the property address, not the homeowner, so it transfers with a sale, according to the IBHS fundamentals page (opens in a new tab). If you're buying a FORTIFIED home, get a copy of the certificate and its expiration date and give it to your insurer.
Questions to ask your Alabama insurance agent
- Is the insurer admitted in Alabama, or is this a surplus lines policy?
- Does the insurer apply the FORTIFIED discount to the wind portion or the whole premium?
- Which FORTIFIED level and roof age will appear in my rating record?
- What percentage applies to my home, and when does it take effect?
- How will the discount show on my declarations page?
- Does my policy have a separate wind, hail or hurricane deductible?
- Is my roof valued at replacement cost or actual cash value after a claim?
- Does my policy include a FORTIFIED endorsement, and what does it cost?
- What does the insurer need when my designation is renewed?
Riskado's directory lists insurance agencies in Alabama by city and category. Before you share documents, confirm the agent's license with the Alabama insurance license lookup (opens in a new tab).
Check what you know about Alabama FORTIFIED roofs
Frequently asked questions
How much does a FORTIFIED roof save on insurance?
The benchmark discount is 20% to 35% of the wind portion of the premium for FORTIFIED Roof, depending on roof age, under the ALDOI table in the May 2025 report. Your dollar saving depends on how large the wind portion of your premium is, which is usually higher on the coast.
Is there a free roof program in Alabama?
Strengthen Alabama Homes pays 100% of the cost of reaching FORTIFIED Roof up to $10,000, for eligible homeowners in counties on its schedule. You still pay the evaluation fee and any cost above the award.
Is a FORTIFIED roof worth it?
It depends on your wind premium, the cost of the work and how long you'll stay in the home. A study from the University of Alabama found that FORTIFIED homes sell for nearly 7% more than non-FORTIFIED homes, according to the Strengthen Alabama Homes program page (opens in a new tab), and the ALDOI report found FORTIFIED Roof homes had 20% less loss severity than conventional homes in Hurricane Sally.
Can I get the grant if I just filed a roof claim?
No, not if the claim was within the past six months. The program FAQ says you can't receive both grant money and insurance claim money to fortify the same home in that period.
Before you sign a roofing contract
Check that your county is on the current grant schedule, line up an approved evaluator before work starts, and confirm your insurer is admitted in Alabama. Keep the IBHS certificate somewhere you can find it, send it to your insurer, and put the five-year expiration date on your calendar.
Key terms
Tap a term to see what it means.
FORTIFIED. A voluntary construction and re-roofing program from IBHS that strengthens homes against high wind, hail and hurricanes.
IBHS. The Insurance Institute for Business and Home Safety, which sets the FORTIFIED standards and issues designation certificates.
FORTIFIED Roof. The first level, which strengthens the roof deck connections, roof edges and gaps in the roof deck.
FORTIFIED Silver. The second level, which adds protection for windows, doors and other openings.
FORTIFIED Gold. The highest level, which adds a continuous load path from roof to foundation.
Wind portion. The part of a homeowners premium that pays for wind and hurricane coverage.
Admitted carrier. An insurer licensed in Alabama and subject to its rate rules, which must honor the FORTIFIED certificate.
Redesignation. The inspection that renews a FORTIFIED certificate after five years.
FORTIFIED endorsement. Optional coverage that pays to upgrade a roof to FORTIFIED when a covered loss requires replacement.