Maryland Homeowners Insurance: What It Costs, What It Covers, Rate Increases and State Laws
Riskado
Maryland state law does not require you to carry homeowners insurance, but mortgage lenders commonly require it as a condition of the loan, according to the Maryland Insurance Administration (opens in a new tab). A standard policy covers your house, other structures, belongings, extra living costs after a covered loss, personal liability, and medical payments to others. Flood and earth movement are excluded, and sewer backup is an add-on you choose. For 2023, the average Maryland HO-3 premium was $2,134, compared with $1,731 nationwide, according to the NAIC homeowners report (opens in a new tab). Your own price depends on your home, location, roof, claims history, and deductible.
Key takeaways
- Is it required?Maryland law does not require homeowners insurance, but mortgage lenders commonly require it as a condition of the loan.
- What a policy coversYour house, other structures, belongings, extra living costs after a covered loss, personal liability and medical payments to others.
- What is left outFlood and earth movement are excluded, and sewer backup is an add-on you choose.
- Average premiumThe 2023 average Maryland HO-3 premium was $2,134, compared with $1,731 nationwide.
- Your own priceIt depends on your home, location, roof, claims history and deductible.
Is homeowners insurance required in Maryland?
The requirement comes from your loan, not from state law. Homeowners insurance is not legally required once a mortgage is paid off, according to the MIA's paid-off-mortgage advisory (opens in a new tab). While a loan is in place, lenders generally require property insurance to protect the home securing it, and a lender can buy lender-placed insurance if your coverage lapses, according to the Consumer Financial Protection Bureau (opens in a new tab).
Maryland limits how much insurance a lender can demand. Under Maryland Commercial Law § 12-312 (opens in a new tab), a lender cannot require insurance on the improvements for more than their replacement value. In practice, if your loan balance is higher than what it would cost to rebuild the house, the lender cannot require coverage equal to the loan, as the MIA's first-time homebuyer tips (opens in a new tab) explain. The land itself doesn't burn down, so it isn't part of the rebuilding cost.
Even without a mortgage, a policy is what protects your house, your belongings, and you from a liability claim. Whether to keep one after payoff is your decision.
What a standard Maryland homeowners policy covers
The HO-3, or Special Form, is the policy form behind the averages above. It generally works this way, according to the MIA Consumer Guide to Homeowners Insurance (opens in a new tab):
- Dwelling: the house is covered against all perils except those the policy specifically excludes.
- Other structures: detached garages, sheds, fences, or pools are covered when damaged by a covered peril.
- Personal property: your belongings are covered against the named perils listed in the policy, subject to sublimits.
- Additional living expenses: the extra cost of living somewhere else is covered when a covered loss makes the home uninhabitable.
- Personal liability: covers accidental bodily injury or property damage you are legally liable for, including defense costs subject to policy terms.
- Medical payments: pays for certain injuries to other people regardless of fault, but not for you or your household.
The dwelling and your belongings are treated differently. The house is protected unless a peril is excluded, while your belongings are protected only against the perils the policy lists. Ask whether your belongings would be paid at replacement cost or actual cash value, since that changes what a claim pays for older items.
What standard homeowners insurance leaves out
Several common causes of damage fall outside a standard policy. The MIA consumer guide (opens in a new tab) lists flood, earthquake and other earth movement including mudslides, neglect, wear and tear, deterioration, freezing of an unoccupied building, and some ordinance-related losses as common exclusions or limitations.
Rising-water flood damage is excluded, so flood protection takes a separate flood policy. Riskado's Maryland flood insurance article explains how that coverage works and how to check your flood map.
If you run a business from home, business property and liability may be excluded or limited, according to the MIA's homeowners page (opens in a new tab). Ask an agent how your policy treats home-business equipment and visiting clients.
Does Maryland homeowners insurance cover sewer backup?
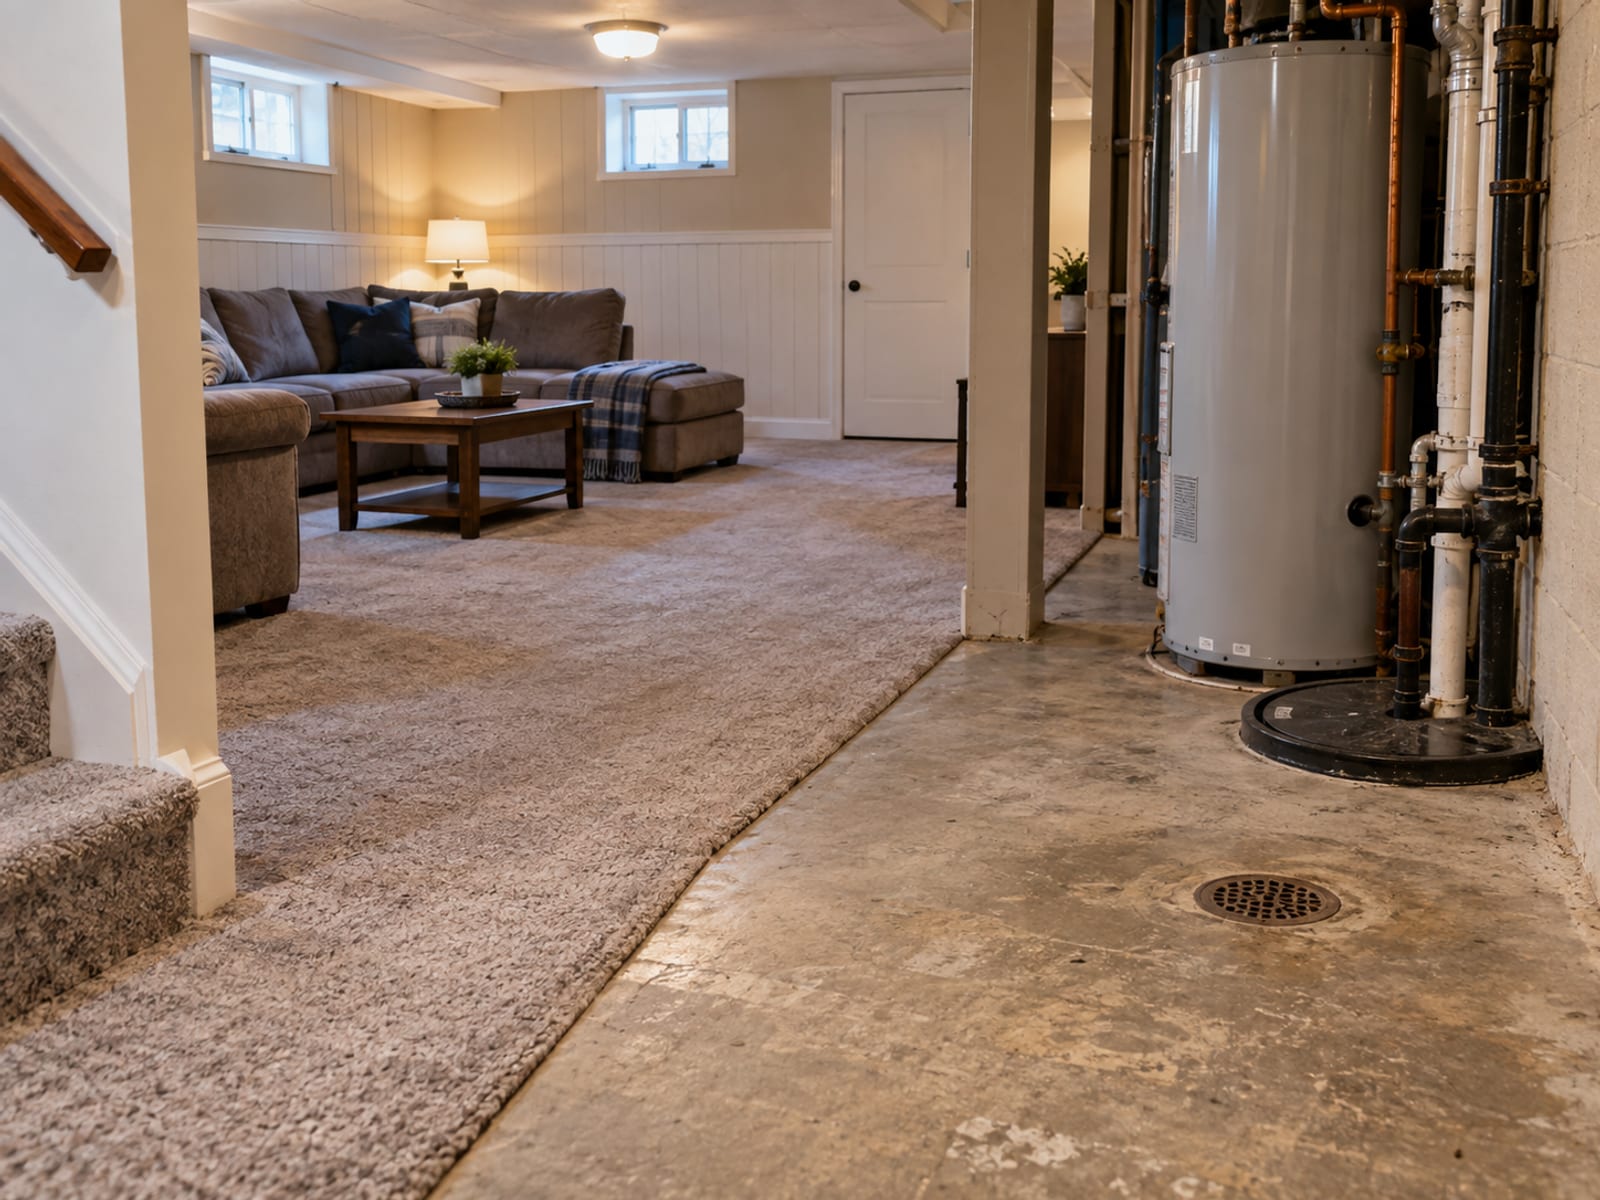
Only if your policy includes it. Sewer or drain backup is a different kind of water loss from flood or seepage, and it is not automatically part of every policy. Maryland insurers must offer sewer or drain backup coverage in writing at application and at renewal, and the coverage may carry an extra premium and its own deductible, according to the MIA's Flood Damage vs. Water Damage page (opens in a new tab).
If you have a finished basement, check your renewal paperwork for that written offer and ask what the coverage limit and deductible would be.
How much does homeowners insurance cost in Maryland?
The average 2023 premium for owner-occupied HO-3 policies in Maryland was $2,134. The countrywide HO-3 average was $1,731, so Maryland's average ran $403 higher, about 23% above the national figure, according to the NAIC 2023 homeowners report (opens in a new tab).
Those are statewide averages for one policy form in one year. They blend rowhouses in Baltimore, waterfront homes on the Eastern Shore, and farmhouses in Western Maryland, so they cannot tell you what your own home will cost to insure. For that, you need quotes on your address, coverage amount, and deductible.
Why are Maryland homeowners insurance rates increasing?
A renewal increase without a claim can come from a general rate increase the insurer filed. Insurers file their rates, and the MIA reviews the filings and supporting data to judge whether rates are excessive, inadequate, or unfairly discriminatory, according to the MIA's rate increase advisory (opens in a new tab). The MIA reviews increases; it does not set each household's premium.
The same advisory lists the pressures behind general increases:
- Inflation and higher repair costs.
- Higher prices for lumber, drywall, paint, and other materials.
- Higher contractor labor costs.
- More frequent or severe storms and more claims.
- Higher business costs such as wages, electricity, and mailing.
- Higher home values, which raise dwelling coverage amounts.
- Reserves for catastrophic losses such as hurricanes.
- Lower investment income.
The market has also tightened. In the MIA's 2024 market hardening survey (opens in a new tab), 23 of 29 responding carriers said they restricted new business or renewals in some way based on distance to the coast or water exposure. Carriers also reported roof-age restrictions, higher deductibles, and more selective underwriting, with coastal restrictions appearing most often on the Eastern Shore, along the Chesapeake Bay and Atlantic coast, and in Worcester County.
If you want the specific figure behind your own increase, look at your renewal notice or ask the insurer for its dated rate filing.
What affects your Maryland homeowners premium?
Insurers price your home using territory, construction type, the age of the house, fire protection, replacement cost, roof condition and age, property condition, claims history, coastal exposure, and the deductible you choose, according to the MIA's Understanding Homeowners Insurance Rates (opens in a new tab).
Credit history is not on that list. Insurers are not allowed to use credit history to refuse Maryland homeowners coverage, cancel a policy, or set the premium, according to the MIA (opens in a new tab).
Loss history is a different matter. Insurers may review your claims history and the property's own loss history through reports such as CLUE, run by LexisNexis Risk Solutions, and ISO A-PLUS, according to the MIA consumer guide (opens in a new tab). A CLUE report is a record of past claims, not a credit report. If an insurer refuses coverage because of one of these reports, you are entitled to see the information behind the decision.
Wind and hurricane deductibles in Maryland
Some policies use a separate deductible for wind, hurricanes, or other storms instead of the general all-perils deductible. That deductible can be a flat dollar amount or a percentage of the dwelling limit.
When a policy requires a percentage hurricane or other-storm deductible, it cannot exceed 5% of the coverage limit unless the Insurance Commissioner approves it in writing, according to the MIA consumer guide (opens in a new tab). You can choose a deductible above 5% voluntarily. If the insurer requires a percentage deductible, it must send an annual statement explaining how the deductible applies.
In the 2024 MIA survey (opens in a new tab), 15 carriers reported mandatory wind or hurricane deductibles ranging from 1% to 5%, with requirements varying by policy type, home type, county, and closeness to the coast.
Cancellation and nonrenewal rules
Maryland law limits when and how an insurer can end your coverage. Under Insurance Article § 27-602 (opens in a new tab), an insurer generally must give at least 45 days' notice before cancelling for a reason other than nonpayment or before nonrenewing. Cancellation for nonpayment generally requires at least 10 days' notice. The notice must also tell you about your possible right to replacement coverage through the Maryland Property Insurance Availability Act or another eligible plan.
Midterm cancellation is limited to specific reasons under the same section: material misrepresentation or fraud, a risk-related matter threatening public safety, a change in risk that increases the hazard, nonpayment, and conviction of arson.
Weather claims have their own rule. Under Insurance Article § 27-501 (opens in a new tab), an insurer may not cancel or refuse to renew based on weather-related claims unless you had three or more in the preceding three years. One exception applies: if the insurer gave you written notice of reasonable repairs that would have prevented a loss and you didn't make them, that weather claim can count. Claims more than three years before the policy or renewal date generally cannot be the basis for cancellation or nonrenewal. More detail on claims-history notices is in COMAR Title 31, Subtitle 15 (opens in a new tab).
If you receive a nonrenewal notice, read the stated reason and compare it with these rules. You can contact the MIA if the reason doesn't fit.
What if private insurers decline your home?
Underwriting rules differ from company to company, so the first step after a decline is to contact other insurers or agencies, according to the MIA's advisory on problems obtaining a homeowners policy (opens in a new tab).
If private coverage stays out of reach, the Maryland Property Insurance Availability Program, known as the Joint Insurance Association (JIA), may provide limited property coverage. The JIA can issue dwelling property, homeowners, and commercial property policies to applicants who meet its underwriting guidelines. Coverage may be more restrictive and more expensive because of the risks the JIA takes on. The JIA is a separate program from MAIF, the Maryland Automobile Insurance Fund, which handles auto insurance.
How Maryland homeowners claims should be handled
Maryland law sets standards for how insurers treat your claim. Insurance Article § 27-303 (opens in a new tab) makes it an unfair claim practice to refuse payment for an arbitrary or capricious reason, fail to explain a denial promptly when asked, fail to settle promptly when liability is reasonably clear, or fail to act in good faith on a first-party property claim. Section 27-304 (opens in a new tab) covers similar failures that happen often enough to be a general business practice.
Under COMAR 31.15.07.03 (opens in a new tab), insurers as a general practice should acknowledge a claim within 15 working days unless they pay within that time, affirm or deny coverage within 15 working days after receiving properly completed claim forms or proof of loss, and not unreasonably delay payment when coverage, liability, and damages are reasonably clear.
If you believe an insurer acted in bad faith on your own claim, a complaint under Insurance Article § 27-1001 (opens in a new tab) is filed with the MIA before a court action. The insurer must respond within 30 days after the MIA forwards the filing, and the MIA generally must decide within 90 days of receiving it.
Hover or tap a row to highlight it.
| Rule | Figure | Where it is set |
|---|---|---|
| Notice before cancelling for a reason other than nonpayment, or before nonrenewing | At least 45 days | Insurance Article § 27-602 (opens in a new tab) |
| Notice before cancelling for nonpayment | At least 10 days | Insurance Article § 27-602 (opens in a new tab) |
| Weather-related claims before cancellation or nonrenewal | Three or more in the preceding three years | Insurance Article § 27-501 (opens in a new tab) |
| Required percentage hurricane or other-storm deductible | No more than 5% of the coverage limit unless the Commissioner approves it in writing | MIA consumer guide (opens in a new tab) |
| Acknowledge a claim | Within 15 working days, unless paid in that time | COMAR 31.15.07.03 (opens in a new tab) |
| Affirm or deny coverage | Within 15 working days after properly completed claim forms or proof of loss | COMAR 31.15.07.03 (opens in a new tab) |
| Insurer response to a bad-faith complaint | Within 30 days after the MIA forwards it | Insurance Article § 27-1001 (opens in a new tab) |
| MIA decision on a bad-faith complaint | Generally within 90 days of receiving it | Insurance Article § 27-1001 (opens in a new tab) |
Checking an agent and filing a complaint
Before you buy, you can confirm that an agent, broker, or agency is licensed through the MIA's Company and Producer Search (opens in a new tab), which is updated weekly and shows whether a producer or firm is or was licensed in Maryland. The same search shows whether an insurer is licensed and which lines it can write. The MIA does not rank insurers.
For a complaint about a claim, a cancellation, or a producer, use the MIA's complaint process (opens in a new tab) and include your policy, notices, correspondence, claim documents, producer information, and a clear description of the problem. The property and casualty complaint line is 410-468-2340 or 1-800-492-6116, according to the MIA contacts page (opens in a new tab).
Questions to ask an insurance agency
These questions make quotes easier to compare, and each one ties to a coverage term in the MIA consumer guide (opens in a new tab):
- Which policy form is this, HO-3 or another form?
- Is the dwelling covered at replacement cost or actual cash value, and how is the roof paid?
- What are the exclusions and sublimits?
- Is sewer or drain backup included, and what deductible applies?
- Is there a separate wind, hail, hurricane, or storm deductible, and is it a flat amount or a percentage?
- Does the policy include ordinance-or-law coverage?
- Should jewelry or other high-value items be scheduled separately?
- How are home-business property and liability treated?
- What happens if the house is vacant or unoccupied?
- What claims-history information is the insurer using?
- Are there coastal, roof-age, or property-condition restrictions?
- Does the policy meet my lender's requirements?
- If private insurers decline, does the home qualify for the JIA?
Bring your declarations page, any renewal or nonrenewal notice, your lender's insurance requirements, roof age and material, the year built and major updates, prior claims, and a home inventory with photos and receipts. Riskado's directory lists insurance agencies across the US, including Maryland agencies by city and category.
Check what you know about Maryland homeowners insurance
Frequently asked questions
Can my insurer cancel my policy in the middle of the term?
Only for specific reasons under Insurance Article § 27-602 (opens in a new tab), such as nonpayment, fraud or material misrepresentation, or a change that increases the hazard. Nonpayment cancellations generally require at least 10 days' notice.
Does homeowners insurance cover earthquake damage in Maryland?
Standard policies generally exclude earthquake and other earth movement, including mudslides, according to the MIA consumer guide (opens in a new tab). Ask an agent whether an earthquake endorsement is available.
Is the Maryland JIA the same as MAIF?
No. The JIA handles property insurance for homes and businesses that cannot get private coverage, while MAIF is the Maryland Automobile Insurance Fund for auto coverage, according to the MIA (opens in a new tab).
Can I see what's on my CLUE report if I'm turned down?
Yes. If an insurer refuses coverage based on a loss-history report, you are entitled to access the information that led to the decision, according to the MIA consumer guide (opens in a new tab).
Before your next renewal
Pull out your declarations page and check four things: your deductibles, whether sewer backup is included, how the roof would be paid, and whether flood coverage is a separate policy. Then compare that with a quote or two from licensed agencies, and keep any notice from your insurer, since the dates on it matter under Maryland law.
Terms used in this guide
Tap a term to see what it means.
HO-3 (Special Form). The common homeowners policy form that covers the house against all perils except those the policy excludes and belongings against the named perils it lists.
Additional living expenses. The extra cost of living somewhere else when a covered loss makes the home uninhabitable.
Sewer or drain backup coverage. Coverage for water that backs up through sewers or drains, offered as an add-on that may carry its own premium and deductible.
Hurricane or other-storm deductible. A separate deductible for wind, hurricanes or other storms, as a flat amount or a percentage of the dwelling limit.
Lender-placed insurance. Coverage a lender buys when the borrower's own coverage lapses.
CLUE report. A record of past claims on you or the property, run by LexisNexis Risk Solutions; it is not a credit report.
Joint Insurance Association (JIA). The Maryland Property Insurance Availability Program, which may provide limited property coverage when private insurers decline.
Declarations page. The page of a policy that lists the coverages, limits and deductibles.